Agentic commerce in the UAE and Saudi Arabia: what merchants and banks should prepare
Agent-ready checkout in the Gulf means more than accepting international cards. It means local schemes, instant account payments, consent rules and bilingual data agents can read.
In this essay
Agentic commerce in the UAE and Saudi Arabia has to fit local payment infrastructure, not only global card networks: national card schemes (Jaywan and mada), instant account-to-account systems (Aani and Sarie) and open finance frameworks supervised by the Central Bank of the UAE (CBUAE) and the Saudi Central Bank (SAMA). Merchants should prepare bilingual structured product data, a checkout agents can call, and a clear approval step for account payments. Banks and payment providers should prepare agent identity checks, tokens for domestic schemes and consent records that show what a customer authorized.
The global agent protocols are still settling, so this guide is a readiness checklist anchored in what regulators and scheme operators have published.
What payment infrastructure will agents meet in the UAE?
The regulator. The CBUAE licenses retail payment services, a category that covers activities including merchant acquiring, payment initiation and payment token services. CBUAE: licensing Any agent payment role, from initiating account payments to issuing tokens, sits inside that perimeter.
Jaywan, the national card scheme. On July 20, 2026, the CBUAE announced that nationwide issuance of Jaywan, the UAE's first national card scheme, had begun in phases through banks, licensed financial institutions and exchange houses, with acceptance at point of sale, e-commerce, ATMs and digital wallets. CBUAE: Jaywan launch Al Etihad Payments' Jaywan materials describe EMV chip technology, tokenization, fraud monitoring, tap-to-pay and mobile-wallet integration. Al Etihad Payments: about Jaywan
Aani, the instant payment platform. Al Etihad Payments lists proxy payments, QR code payments and Request to Pay among Aani's services, and describes merchants being paid through static or dynamic QR codes, a request the customer accepts in the app, or a merchant tag. Al Etihad Payments: Aani
Open finance. The CBUAE Open Finance Regulation separates Data Sharing from Service Initiation, requires at least two-factor authentication, and requires consent that is purpose-specific and can be withdrawn, including parameters for recurring transactions. CBUAE Rulebook: Open Finance Regulation UAE open finance pay by bank covers the checkout gates in detail.
What payment infrastructure will agents meet in Saudi Arabia?
Sarie, the instant payment system. SAMA describes Sarie's instant payments as a national system launched in 2021 for low-value transfers of SAR 20,000 or less between local banks, processed instantly, 24/7. SAMA: Sarie SAMA's rulebook also instructs banks to verify accounts before adding and activating beneficiaries for transfers through the instant payment and RTGS systems. SAMA Rulebook: account verification
mada and electronic payments. SAMA reported that electronic payments made up 85% of retail payments in 2025 and linked the growth to mada activity, especially at point of sale and in e-commerce. SAMA: e-payments in 2025 What mada is explains how the network works.
Open banking. SAMA began licensing fintech companies to provide open banking services in March 2026, after the sandbox phase SAMA: open banking licensing, and its September 2026 forum with banks focused on readiness for Payment Initiation Services. SAMA: open banking forum Saudi payment initiation readiness goes deeper.
| Building block | UAE | Saudi Arabia | Why it matters for agents |
|---|---|---|---|
| Regulator | CBUAE | SAMA | Decides which licensed entity can initiate payments or issue tokens |
| National card scheme | Jaywan | mada | Domestic routing, tokens and dispute evidence |
| Instant account payments | Aani | Sarie | Account payments the customer approves, with beneficiary checks |
| Open finance | Open Finance Regulation | Open banking licensing, payment initiation next | Consent records that work like a mandate |
What does agent-ready checkout mean in the Gulf?
Global agent payment programs mostly start from cards. In the Gulf, four local questions sit on top of that:
- Does the agent credential keep the domestic route? Domestic scheme cards can be co-badged with an international network. When an agent pays with a network token, check whether the transaction runs on Jaywan or mada or shifts to the international network. The Jaywan control room explains why routing evidence by rail matters.
- Where does the buyer approve account payments? Request to Pay and open finance initiation leave the final approval with the customer, in the Aani app or through bank authentication. For agents, that is a useful design: the agent prepares the payment and the person approves it.
- Does the agent's mandate fit the consent? UAE open finance consent is purpose-specific and can include recurring parameters. Keep any agent instruction inside the consent the customer actually gave, and record both.
- Can the agent read your catalog in both languages? Feeds should carry Arabic and English titles, prices in AED or SAR shown the way you show them to buyers, and delivery promises by city or emirate.
What should merchants prepare?
| Area | Readiness check |
|---|---|
| Product data | Bilingual feed with stable IDs, current prices, stock and delivery estimates |
| Checkout | Start with agent discovery and redirect; add agent checkout through your PSP when it supports it |
| Local payment methods | Jaywan and mada acceptance confirmed with your acquirer, including e-commerce |
| Account payments | Aani or pay by bank where your provider offers it, with the order reference carried through |
| Policies | Delivery, returns and cancellation terms in structured fields, not only in page text |
| Refunds | A refund route for instant account payments, which settle as transfers rather than card payments |
| Bot management | Allow agents that identify themselves; keep rate limits and fraud checks for the rest |
The general merchant list is in preparing an online store for AI shopping agents.
What should banks, issuers and PSPs prepare?
- Agent identity. Decide how you will recognize an agent, the customer behind it and its permissions before approving its transactions. KYA as an identity control plane covers the problem.
- Domestic tokens. Ask your scheme operator and token service provider how agent tokens are provisioned for Jaywan or mada cards, and report outcomes by rail.
- Customer controls. Give customers a screen that lists each agent's permissions and limits, with one-tap revocation.
- Real-time limits. Apply per-agent caps and merchant category rules at authorization, not only in the agent platform.
- Account verification. For agent-initiated account payments, keep beneficiary checks before payment; Saudi rules already require verification before activating beneficiaries.
- Licensing map. For each agent flow, name the licensed entity that initiates the payment, issues the token and holds funds.
- Dispute evidence. Store the instruction, consent and authorization together so a disputed agent purchase can be explained; see agentic commerce chargebacks and liability.
How should a Gulf agentic commerce pilot start?
Keep the first pilot narrow: one product category with low return rates, card payments through your existing acquirer, buyer approval on every purchase, and agent orders tagged so you can compare conversion, refunds, disputes and support contacts with other channels. Add account payments once refunds and reconciliation work. For B2B buyers, the controls in agentic commerce in B2B procurement apply unchanged.
FAQ
Is agentic commerce available in the UAE and Saudi Arabia?
The local building blocks are live or rolling out: national card schemes, instant payments and open finance frameworks. Agent programs from global providers vary by country, so confirm availability with your acquirer or PSP.
Can AI agents pay with Jaywan or mada cards?
Ask your issuer and acquirer. Co-badged cards may be reachable through international agent token programs, but whether the payment keeps domestic routing depends on token provisioning, so test it by rail.
Can an AI agent use Aani or Sarie?
An agent can prepare an account payment, but leaving approval with the customer, in their payment app or through a licensed initiation provider, keeps the person in control, which suits early pilots.
Who regulates agent payments in the UAE and Saudi Arabia?
The CBUAE licenses retail payment services in the UAE, including payment initiation and payment token services. SAMA supervises payments and licenses open banking providers in Saudi Arabia.
What should a Gulf merchant do first?
Publish an accurate bilingual product feed, confirm Jaywan or mada e-commerce acceptance with your acquirer, and make delivery and return policies machine-readable.
Closing thought and further reading
Agent-ready checkout in the Gulf means more than accepting international cards. It means local schemes, instant account payments, consent rules and bilingual data agents can read.
Ideas that continue the thread.
View all essays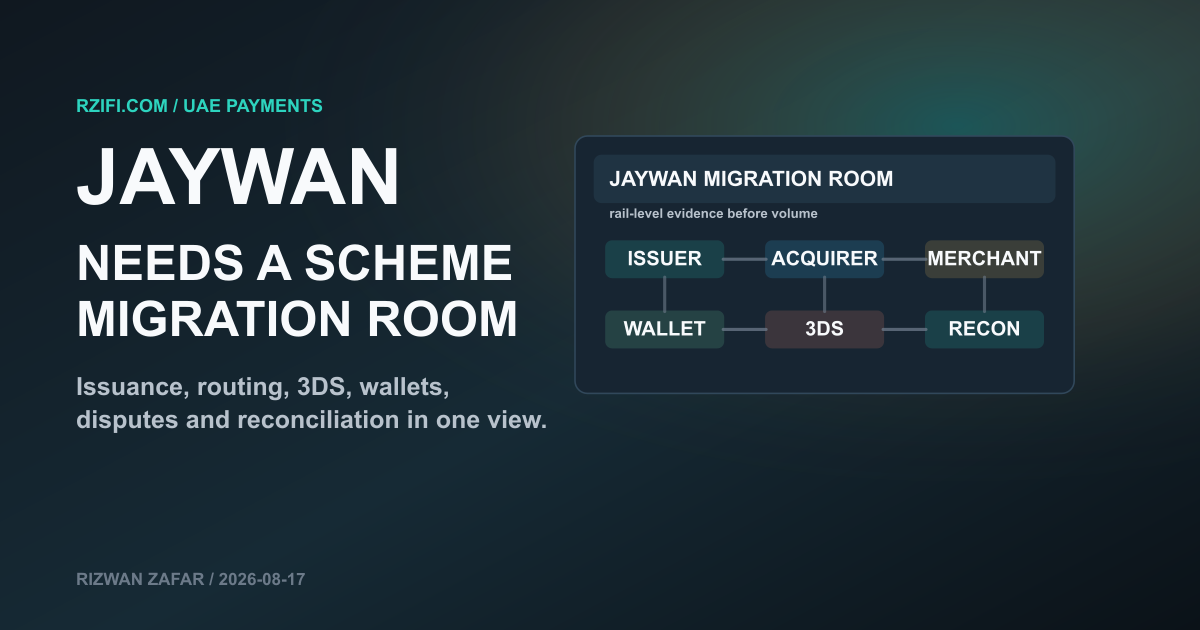
Need help applying this to your business?
Explore practical support for payment operations, product decisions, program delivery and AI automation, grounded in the challenges behind this essay.